Using ADU Rental Income to Qualify
Buying a Home with a Backhouse? How 2026 Lending Rules Let You Use ADU Rent to Qualify
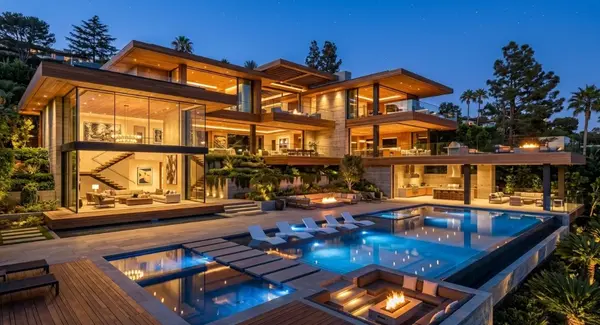
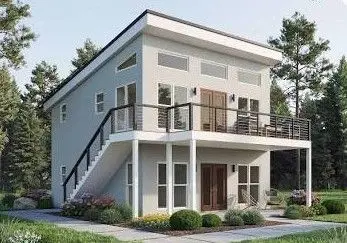
Across Los Angeles—from the San Fernando Valley to the Westside—properties with an Accessory Dwelling Unit (ADU), guest house, or converted garage are among the most sought-after listings on the market. Buyers love the flexibility of having a separate space that can generate monthly rental income to help offset a California mortgage.
Historically, however, conventional mortgage guidelines lagged behind California’s ADU boom. Even if a property had a fully permitted, turn-key backhouse, traditional lenders generally refused to count that projected rent toward a buyer's purchasing power on a standard single-family home loan.
Thanks to Fannie Mae’s updated rental income guidelines, that roadblock has finally been removed. If you are shopping for a home with an ADU in 2026, here is how you can leverage that backyard unit to boost your qualifying income—and the specific fine print you need to know before writing an offer.
How the New ADU Income Rule Works
Under Fannie Mae’s updated Selling Guide rules (B3-3.8-02), borrowers purchasing a 1-unit principal residence with an existing ADU can now use the projected rental income from that ADU to help qualify for a conventional mortgage.
Even if the ADU is currently vacant at the time of purchase, your lender can order a Single-Family Comparable Rent Schedule (Form 1007) alongside the standard appraisal. The appraiser will determine the fair market monthly rent for the ADU, and the lender can apply 75% of that gross market rent toward your qualifying income (the remaining 25% is held back by underwriters to account for standard vacancy and maintenance costs).
The Fine Print: 4 Rules Every Buyer Must Know
While this rule is a massive win for Los Angeles buyers, underwriters must follow strict guardrails:
-
The 30% Income Cap: The qualifying rental income from the ADU cannot exceed 30% of your total qualifying income on the loan application. In short, the ADU rent can give your debt-to-income (DTI) ratio a significant boost, but it cannot be your primary source of income.
-
One ADU Maximum: California law now allows homeowners to build both a standard ADU and a Junior ADU (JADU) on a single-family lot. However, for mortgage qualification purposes, Fannie Mae only allows you to count the rental income from one ADU, even if the property has two legal accessory units.
-
Permits & Zoning Compliance: To count the income, the ADU must be legally permitted (or verify compliance under local zoning requirements) and provide fully independent living facilities—meaning its own sleeping, bathing, and kitchen/cooking areas. Unpermitted "bootleg" garage conversions will not qualify for the rental income boost without proper appraisal verification.
-
Long-Term Rent Only (No Airbnb Projections): Appraisers must base the ADU’s rental value on traditional long-term market rents. Lenders will not allow you to use projected short-term vacation rental (Airbnb/VRBO) income from a vacant ADU to qualify for the purchase.
What This Means for Your Home Search
In a high-cost market like Los Angeles, adding $1,800 to $2,500+ per month in qualifying rental income can easily translate into $150,000 to $250,000+ in additional purchasing power—allowing you to afford a higher-priced property that practically pays for the difference itself.
Thinking about buying or selling a home with an ADU? Before you tour properties or list your home, reach out to our team so we can run the numbers, verify permit records, and structure your financing strategy to maximize your buying power.
Categories
Recent Posts
GET MORE INFORMATION